Quartz's AI finance app and the line with regulated advice
Quartz has launched a UK app that pairs account aggregation with an AI assistant, Charlie, after a £2.75m raise. Its FCA registration covers account information, not investment advice.
By FinTechPulse Editorial
- Published
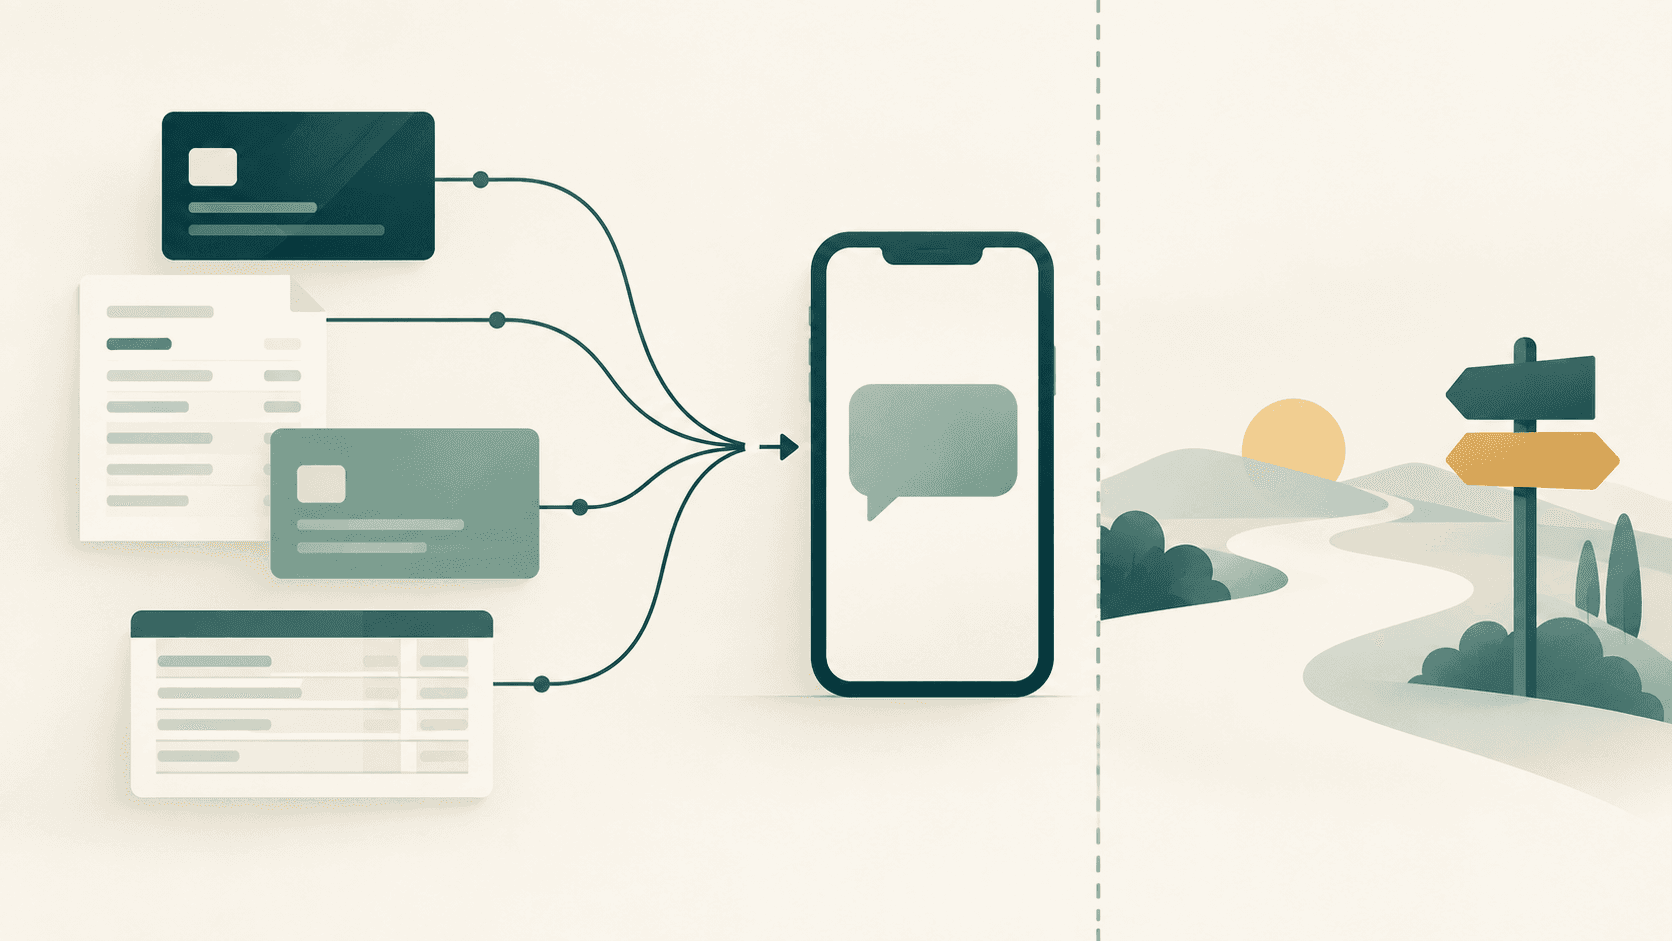
Quartz Digital Ltd launched its wealth app to UK users on 16 September 2026, alongside a £2.75m pre-seed funding round. The app pulls a person's accounts into one place and adds an AI assistant called Charlie, which the company says produces personalised explanations and insights. Quartz says it is registered with the Financial Conduct Authority (FCA) to provide account information services. It also says it does not give financial advice.
Those two statements matter to UK adults considering the app, which Quartz says is intended for UK residents aged 18 or over. Eligibility is not the same as access: as at 21 September 2026, Quartz was admitting wait-list members in invitation-only batches. Charlie's output is built from a user's own financial data, goals and risk preferences. The FCA registration Quartz relies on covers one narrow activity, and the line between personalised information and a regulated recommendation is set by the substance of what is said, not the label on it.
What Quartz launched after its £2.75m raise
The round was led by Daphni, with Outward VC, K Fund and angel investors including Philippe Gelis and Gilles BianRosa taking part, according to Quartz's announcement. The brief for this article rounds the figure to £2.7m; the company's own figure is £2.75m. Spanish outlet Cinco Días reported the round as €3.2m on the same day.
Quartz says it has been testing since the start of 2026 and that more than £10m of members' assets were tracked on the platform by 16 September 2026. That is a company-reported figure. It is not assets under management, because Quartz does not hold or manage the assets, and its calculation has not been independently verified.
Access is not yet open to everyone. From 16 September 2026, Quartz has been admitting wait-list members in invitation-only batches. As at 21 September 2026 it advertised a 14-day free trial, then £16.99 a month or £169.99 a year. Subscription prices can change, so readers should check the current terms with Quartz.
How Quartz combines aggregation with Charlie
The app aggregates payment accounts, such as current accounts, and also covers non-payment assets: investments, pensions, cryptoassets, property and manually entered holdings. Quartz advertises more than 250 account connections and more than 1,000 Charlie sessions as at 21 September 2026; both are the company's own figures. It says its UK Open Banking connections use Yapily as a technology provider. Open Banking is the UK framework that lets a customer permit a regulated provider to read data from their bank account.
Quartz says Charlie draws on connected accounts, transaction history, stated goals, risk preferences and constraints to generate portfolio-related explanations and insights. Its privacy policy describes the use of automated tools, including AI, to analyse personal data and produce factual insights such as fee and investment-return analysis.
The dataset behind this is broad. The privacy notice says the app may process identity details, income, estimated wealth, account identifiers, balances, transactions, holdings, the questions users put to Charlie, device identifiers and usage data. Quartz also says its payment-account access is read-only, and that the app cannot move, trade or withdraw users' money. Its terms say the service does not currently execute trades or investments.
The sources reviewed do not say which AI model powers Charlie, how its outputs are checked, or how often it is wrong. They also do not say whether user data or prompts are used to train third-party models. Quartz says account and portfolio information can be refreshed every 15 minutes; that claim has not been independently verified and may vary by provider.
What the FCA registration covers
Quartz Digital Ltd gives its company number as 16253590 and its FCA reference number as 1043690. Companies House records it as an active company incorporated in England and Wales on 14 February 2025. Companies House says it does not verify all the information filed with it.
The FCA defines an account information service as an online service giving consolidated information on one or more payment accounts held with other payment service providers. Such services have been regulated under the Payment Services Regulations 2017 since 13 January 2018. Quartz says it is registered under those regulations.
The FCA says a firm providing only account information services may become a registered account information service provider. Such firms have no capital requirement and meet fewer conditions than authorised payment institutions. The FCA also says a registered provider's only payment service can be account information services.
Two points follow, and both carry weight for readers:
- Registration is not approval of the whole app. The FCA's regime covers retrieving and consolidating payment-account data. It does not, by itself, give permission to recommend particular investments.
- Not every connection falls under it. Quartz's app terms separate regulated account information services for payment accounts from its aggregation of investment, pension and other non-payment accounts, which they describe as outside that regime.
Quartz's own wording varies. Its footer and marketing pages say it is "registered" with the FCA, which fits the registered category. Its app terms and privacy notice also use "authorised and regulated" or "authorised" when describing its status. The FCA distinguishes registered account information service providers from authorised payment institutions, so the broader wording should not be read as a wider permission.
FinTechPulse could not retrieve the FCA Financial Services Register entry for reference number 1043690 during research. The FCA's consumer guidance says people should check that a firm and its relevant permissions appear on the Register. Status, permissions and any requirements should be checked there directly. No evidence reviewed shows that Quartz holds permission to advise on investments, and none should be inferred from its registration. The date its registration took effect could not be established.
Where personalised insight approaches advice
Quartz markets Charlie as personalised guidance based on users' portfolios and goals, including identifying risks and opportunities. Its website and terms also say Quartz is not a financial adviser and does not make personal recommendations to buy, sell or hold investments. Its terms add that content may be incomplete or inaccurate, is not guaranteed to meet a user's needs and should not be treated as financial advice.
These statements are not necessarily inconsistent. The FCA Handbook, in its perimeter guidance at PERG 8.30B, says a personal recommendation includes a recommendation about a particular investment that is presented as suitable for a person or based on that person's circumstances. The guidance cited here took effect on 23 February 2018, and the Handbook page was last updated on 27 March 2026. The FCA's illustrative examples in PERG 8 Annex 1 show how references to an individual portfolio and investment purposes can affect the analysis. The FCA has also published material on the boundary between support, guidance and advice.
The test turns on content and context. A disclaimer alone does not establish that an output falls outside the regulated perimeter, and the answer also depends on the communicator's authorisation status. A factual analysis of fees paid or returns achieved is a different thing from a message about the merits of buying, selling or holding a named fund. Quartz's privacy policy describes the first kind of output. The second kind is where the perimeter question arises.
Whether any Charlie response crosses the line cannot be judged from Quartz's published material. It would take transcripts of real outputs, particularly any that name funds, securities or pension actions. The FCA has not made a determination about Charlie's outputs in the sources reviewed.
What users should understand before relying on Charlie
- Information, not a recommendation. By Quartz's own account, Charlie provides information and guidance. A personal recommendation on investments is a regulated activity that requires the right authorisation, which the sources do not show Quartz has.
- If Charlie names a specific investment or action. Where an output points to a particular fund, security, pension action or portfolio change, users should verify the data behind it, such as balances, holdings and any manually entered figures, and consult an appropriately authorised adviser before acting on a specific personal investment recommendation. The FCA's Financial Services Register shows whether a firm is authorised and what permissions it holds.
- Data quality. Quartz says its content may be incomplete or inaccurate. Manually entered holdings depend on what the user typed. The sources do not establish which investment and pension connections use APIs and which use secure web views, or whether every connection supplies complete transaction history.
- Consent. Quartz requires explicit consent to retrieve payment-account information, and its app terms say that consent lasts 90 days unless revoked sooner. Arrangements for non-payment accounts differ by connection type.
- Responsibility. Quartz's terms say users remain responsible for decisions based on app content. Any investment can lose money, and nothing in the sources suggests Charlie's output reduces that risk.
- Cost. As at 21 September 2026, Quartz advertised £16.99 a month or £169.99 a year after a 14-day free trial. The sources reviewed do not establish the renewal arrangements.
Redress is unclear. No evidence was found that the AI-insight service is covered by the Financial Services Compensation Scheme (FSCS), and cover should not be assumed. Whether a complaint about Charlie's investment insights would fall within the Financial Ombudsman Service also depends on the activity and the complaint, and has not been confirmed.
The privacy policy says data may be shared within a Quartz group of companies. The reviewed sources do not name those companies. The date the app terms and privacy policy were last updated is also not shown on the pages.
What to watch
The first item is the Register. The entry for reference number 1043690 will show Quartz's permissions and any requirements, and any later change to them would signal a change in what the firm may do. The second is disclosure: Quartz has not published the model behind Charlie, its accuracy testing or its escalation arrangements. The third is access, since the app is invitation-only for now, and the round's use of funds, valuation and settlement were not disclosed.
The FCA's Financial Services Register and its account information service pages hold the official detail. The PERG 8.30B guidance in the FCA Handbook sets out the personal recommendation test.
Sources
- Quartz launches in the UK with £2.75M to give everyone their own personal banker (opens in a new tab)
Quartz Digital Ltd · · Accessed
- Quartz — Your own personal banker (opens in a new tab)
Quartz Digital Ltd · Accessed
- App Terms (opens in a new tab)
Quartz Digital Ltd · Accessed
- Privacy Policy (opens in a new tab)
Quartz Digital Ltd · Accessed
- QUARTZ DIGITAL LTD overview (opens in a new tab)
Companies House · Accessed
- Account information and payment initiation services (opens in a new tab)
Financial Conduct Authority · · Accessed
- Account information services and payment initiation services (opens in a new tab)
Financial Conduct Authority · · Accessed
- Registered account information service provider applicants (opens in a new tab)
Financial Conduct Authority · · Accessed
- PERG 8.30B Personal recommendations (opens in a new tab)
Financial Conduct Authority · Accessed
- Helping firms provide more support to customers making investment decisions (opens in a new tab)
Financial Conduct Authority · · Accessed
- PERG 8 Annex 1 Examples of what is and is not a personal recommendation and advice (opens in a new tab)
Financial Conduct Authority · Accessed
- Kfund entra en la ‘fintech’ británica de gestión patrimonial Quartz (opens in a new tab)
Cinco Días · · Accessed