Bottomline's Chainlink deal and the messaging-settlement gap
Bottomline's Global Pay Connect promises bank access to blockchain networks through Chainlink. The evidence covers connectivity, not settlement, and UK treatment depends on the asset and activity involved.
By FinTechPulse Editorial
- Published
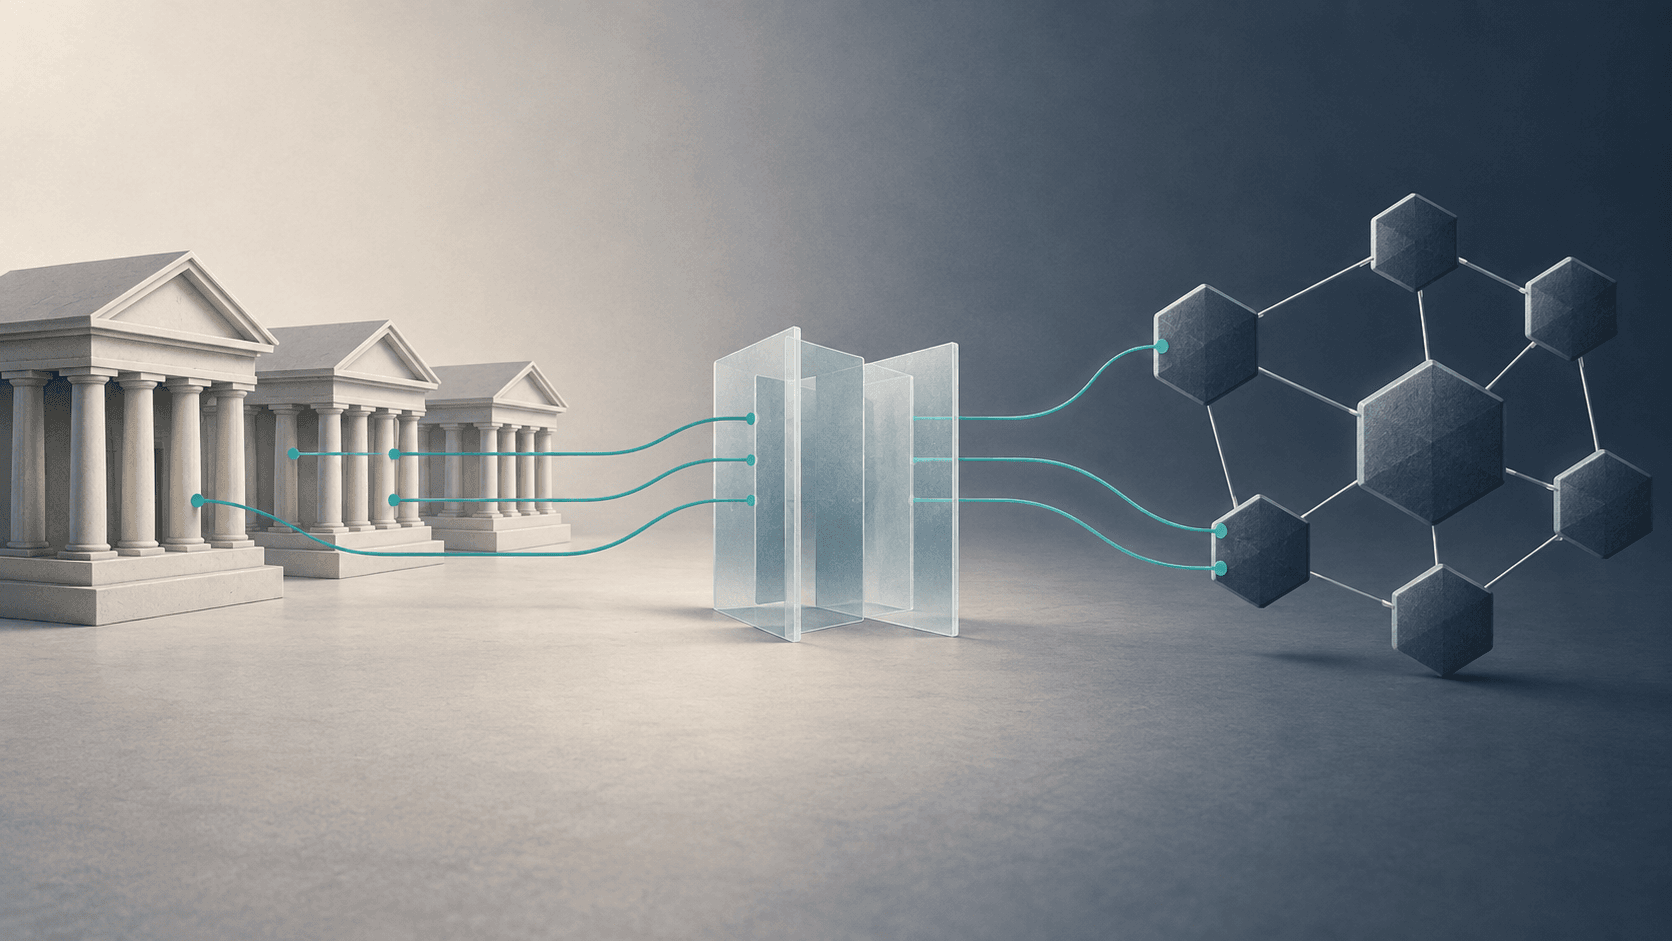
Bottomline Technologies announced Global Pay Connect on 17 September 2026. It is a software-as-a-service (SaaS) platform for payment messaging and connectivity, aimed at financial institutions. The company launched it alongside a Strategic Collaboration Agreement with Chainlink. Bottomline says the agreement lets banks reach multiple blockchain networks through their existing Bottomline connections.
The announcement came from the United States, but Bottomline markets the platform in the UK. It lists Bacs and CHAPS among the schemes the platform supports. For UK banks and payment firms, the question is whether a messaging layer they already use can become a route to tokenised assets. It arrives days before the Financial Conduct Authority (FCA) opens its authorisation gateway for the UK's new cryptoasset regime, on 30 September 2026.
The launch documents establish less than the headline suggests. They describe connectivity and orchestration. They do not name a blockchain, a settlement asset, a live customer or a transaction. This analysis separates what Bottomline has said from what it has shown, then sets out how UK regulation would treat a deployment. All UK regulatory statements are as at 21 September 2026.
What Bottomline says it has launched
Bottomline says Global Pay Connect connects to Swift, SEPA, SIC, Bacs, CHAPS, CHIPS, Lynx, EBICS and host-to-host channels. Its stated functions include:
- ISO 20022 message transformation
- payment-data enrichment
- a Message Vault
- real-time payment visibility
- fraud prevention
- compliance controls
- access to conventional and blockchain-based networks
These are the supplier's own capability claims, and no independent technical testing was located. The sources also differ slightly. The launch release lists CHAPS, CHIPS, Lynx and EBICS, while the shorter FAQ on Bottomline's UK product page names Swift, SEPA, Faster Payments, Bacs and SIC. That may reflect an abbreviated FAQ, but availability of each connection by market and launch date is not disclosed.
Bottomline also cites scale. It says more than $16tn of payments move through its platforms annually. The product page says 15% of international cross-border Swift traffic is sent over Bottomline rails, that its SaaS services process 10 million payments and transactions daily, and that it is a top-three Swift service bureau globally. None of these figures comes with a methodology, a measurement period or independent corroboration. The release does not say whether the $16tn is value messaged, processed or settled.
Where Chainlink fits
The launch release says Chainlink supplies a single, network-agnostic integration model. A bank would connect to several blockchain networks through that one model, using the Bottomline connectivity it already has.
The technical detail is missing. No first-party document identifies which Chainlink components are used. Some promotional coverage has referred to Chainlink's Cross-Chain Interoperability Protocol and Chainlink Runtime Environment. Those names do not appear in the Bottomline release or product page, so they are unverified. The same coverage cites more than 600 banks, a figure with no first-party confirmation tied to Global Pay Connect or its blockchain capability.
Launched, or still a proof of concept?
The sources disagree on maturity, and the disagreement bears directly on the headline claim.
The launch release uses present-tense language. It says the platform enables banks to connect to blockchain networks and access on-chain payment rails. Bottomline's UK product page is more cautious. It says the Chainlink collaboration will enable Bottomline to explore proof-of-concept opportunities that could bridge traditional payment infrastructure and blockchain networks.
That leaves three readings open: a launched general platform, a technically available integration, or a blockchain capability still at proof-of-concept stage. The evidence does not settle which is right. The materials name no supported blockchain, settlement asset, production customer or completed transaction. They also disclose no pricing, availability by jurisdiction, implementation timetable or commercial terms for the Chainlink agreement.
Messaging is not settlement
A payment message is an instruction. Settlement is the final, irrevocable transfer of value, and it needs an asset, a ledger and a party responsible for finality. Global Pay Connect, as described, translates, enriches, monitors and routes messages. The materials do not say that Bottomline or Chainlink performs final settlement or supplies the settlement asset. That is an inference from the functions described and from what is absent, but it is a firm one.
The cited first-party materials also do not say that either product replaces Swift, correspondent banking, central-bank money or other settlement arrangements, or whether deployments would settle in qualifying stablecoins, tokenised commercial-bank deposits, tokenised securities, central-bank money or conventional accounts. They do not say who would execute transfers, control wallets or private keys, perform safeguarding, provide liquidity or bear settlement-finality risk, or whether the platform only routes messages or also orchestrates conditional asset movement through smart contracts.
The established-infrastructure argument is that a common interface could reduce bespoke integrations. Even if that holds, it would not move the asset, liquidity, custody and compliance questions. Those would stay with the institutions involved.
The UK regulatory map
UK regulation attaches to assets and activities, not to blockchain as a technology. HM Treasury says tokenised deposits fall within the established legal definition of a deposit and are regulated accordingly. Qualifying stablecoins and other qualifying cryptoassets are treated under their own regimes.
The Financial Services and Markets Act 2000 (Cryptoassets) Regulations 2026 create regulated activities that would matter to any deployment touching these assets. Full commencement is scheduled for 25 October 2027. The FCA published final policy statements and rules for the regime on 30 June 2026.
| Activity or arrangement | UK position as at 21 September 2026 |
|---|---|
| Tokenised deposits | Remain deposits in financial-services law, per HM Treasury |
| Issuing qualifying stablecoins | New regulated activity, scheduled from 25 October 2027 |
| Safeguarding qualifying cryptoassets | New regulated activity, scheduled from 25 October 2027 |
| Operating a qualifying cryptoasset trading platform | New regulated activity, scheduled from 25 October 2027 |
| Dealing or arranging deals in qualifying cryptoassets | New regulated activity, scheduled from 25 October 2027 |
| Qualifying cryptoasset staking | New regulated activity, scheduled from 25 October 2027 |
| Stablecoins used in payments | Not regulated specifically as payment transactions under the UK payment-services framework; HM Treasury is consulting on bringing certain UK-issued qualifying stablecoins in |
| Payment systems transferring digital settlement assets | HM Treasury can designate them, letting the Payment Systems Regulator (PSR) regulate participants; recognised systemic systems or service providers can come under the Bank of England |
The stablecoin payments entry does not mean stablecoins are unregulated. Existing laws can still apply to the firms, assets and activities involved. HM Treasury intends to regulate the use of certain stablecoins for payments.
Systemic status is a separate step. A UK qualifying-stablecoin issuer can move from FCA supervision to joint FCA and Bank of England regulation if HM Treasury recognises it as systemic. Designation of a payment system is likewise a statutory step. Connecting to a blockchain does not in itself make a platform a designated payment system.
An institutional-only deployment is not automatically outside UK regulation. Customer type can affect territorial scope or available exemptions. Deposit-taking, UK stablecoin issuance, safeguarding and the operation of recognised or designated infrastructure can remain regulated. Whether a given Global Pay Connect deployment performs any regulated activity cannot be established from the announcement. That would depend on the contractual flow, the entities and customer locations, the asset classification and the custody model.
Unresolved risks and responsibilities
The FCA has said banks are important to stablecoin trust, scale and interoperability. Its 2026 policy work also recorded concerns from participants about anti-money laundering, customer due diligence and liability across payment chains.
Those concerns apply directly to a bridge between conventional and blockchain networks. The launch materials do not say how responsibility divides between Bottomline, Chainlink, the financial institution, any token issuer and the blockchain operator, or how identity, customer due diligence and data privacy work when messages cross between the two kinds of network. Wallet security, smart-contract failure, sanctions screening, liquidity and settlement finality are further risks they do not address. Nothing here implies Financial Services Compensation Scheme or Financial Ombudsman Service cover for institutional users.
What to watch next
The FCA authorisation gateway for firms intending to carry out the new cryptoasset activities is scheduled to open on 30 September 2026. HM Treasury's payment-services consultation and its cryptoasset amendments were still developing at the 21 September research cut-off, so final legislation will need checking. The official detail sits with HM Treasury, the FCA and the Bank of England.
On Bottomline's side, the missing evidence falls into two kinds. An architecture document naming the Chainlink components and a supported-network and asset list would clarify the technical scope and the implementation. They would not show that the service is in commercial use. A named production deployment or a verifiable completed transaction would help establish whether Global Pay Connect's blockchain access is a live commercial service or proof-of-concept work.
Sources
- Bottomline launches Global Pay Connect to provide financial institutions with a future-proofed payment messaging ecosystem (opens in a new tab)
Bottomline Technologies, Inc., distributed by GlobeNewswire · · Accessed
- Global Pay Connect (opens in a new tab)
Bottomline · Accessed
- The Financial Services and Markets Act 2000 (Cryptoassets) Regulations 2026: explanatory memorandum (opens in a new tab)
HM Treasury and The National Archives · · Accessed
- Overview of our cryptoassets regime policy statements (opens in a new tab)
Financial Conduct Authority · · Accessed
- Modernising Payment Services Regulation Consultation (opens in a new tab)
HM Treasury · · Accessed
- FCA and the Bank of England set out approach to joint regulation of systemic stablecoin issuers (opens in a new tab)
Financial Conduct Authority · · Accessed
- Roles and responsibilities in payments regulation (opens in a new tab)
Financial Conduct Authority · Accessed
- Stablecoin Sprint (opens in a new tab)
Financial Conduct Authority · · Accessed